Can a Debt Consolidation Loan Help You Get Better Personal Loan Rates?
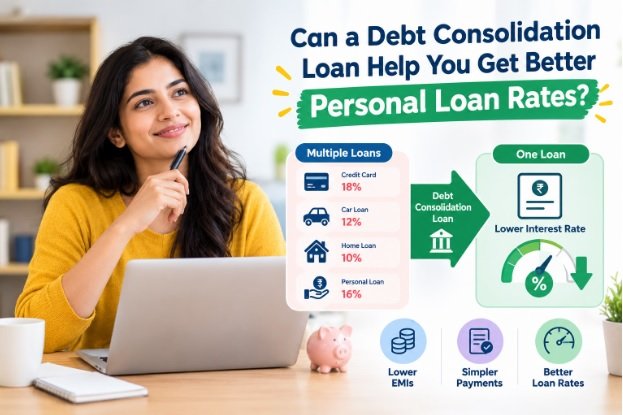
Managing several outstanding debts can make monthly financial planning complicated. Multiple EMIs may have different due dates, interest rates and repayment periods. Consolidating eligible debts into a single borrowing arrangement can simplify repayment, but borrowers should evaluate the complete cost before making a decision.
What Is Debt Consolidation?
A debt consolidation loan is generally used to combine multiple outstanding debts into one repayment structure. Instead of managing several separate obligations, a borrower may use the new loan to repay eligible existing debts and then make one regular EMI.
The main attraction is simplicity. One EMI can make it easier to track payments and organise monthly cash flow. However, consolidation does not automatically reduce the cost of borrowing.
When Can Consolidation Be Useful?
Consolidation may be considered when existing debts carry different interest rates or when several repayment dates make budgeting difficult. For example, a borrower may have outstanding credit card balances and other unsecured borrowing with different payment schedules.
Before selecting a debt consolidation loan, calculate the outstanding principal, remaining interest and applicable closure charges on existing debts. Then compare these figures with the total cost of the new borrowing.
Compare Personal Loan Rates Carefully
Personal loan rates can vary depending on the lender, borrower profile, loan amount, tenure, income and credit history. A lower advertised rate may not always mean a cheaper loan after processing fees and other charges are included.
Bajaj Markets enables users to compare personal loan offers from multiple lenders, with current listed options differing in interest rates, loan amounts and repayment periods.
When comparing personal loan rates, look at the annual interest rate, processing charges, repayment tenure and total payable amount together.
Calculate the Total Cost
Suppose a borrower has three debts with different EMIs. Consolidating them may reduce the monthly payment if the new loan has a longer tenure. However, extending repayment for several additional years can increase the total interest paid.
Therefore, do not judge a debt consolidation loan solely by its lower EMI. Calculate:
- Existing outstanding principal
- Remaining interest
- Closure or foreclosure charges
- Processing fee on the new loan
- New EMI
- New tenure
- Total interest payable
This comparison gives a clearer picture of whether consolidation actually improves the financial position.
Check Your Credit Profile
Credit history can influence loan eligibility and the terms offered by lenders. A borrower with timely repayments and responsible credit utilisation may have a stronger profile.
Before applying, check your credit report for inaccurate information. If there are unresolved errors, addressing them can help ensure that lenders receive accurate information during their assessment.
Avoid Adding New Debt After Consolidation
One common risk is using the new loan to clear existing balances and then accumulating fresh debt. This can increase the overall financial burden instead of solving it.
After consolidating, create a realistic monthly budget and avoid unnecessary borrowing. If credit cards were part of the original debt, review spending patterns to prevent the balances from building up again.
Compare Offers Before Choosing
Bajaj Markets can be useful for comparing available personal loan options in one place. The platform currently lists personal loans from more than 20 lenders, allowing users to review different loan structures before applying.
When comparing personal loan rates, consider the complete repayment cost rather than selecting the first offer with an attractive headline rate.
Final Thoughts
A debt consolidation loan can simplify repayment and may be useful when the new borrowing offers suitable terms. However, consolidation is beneficial only when the overall cost, tenure and repayment structure make financial sense.
Compare personal loan rates, calculate the total payable amount and review all applicable charges before making a decision. With careful planning and disciplined repayment, consolidation can make debt management more organised.